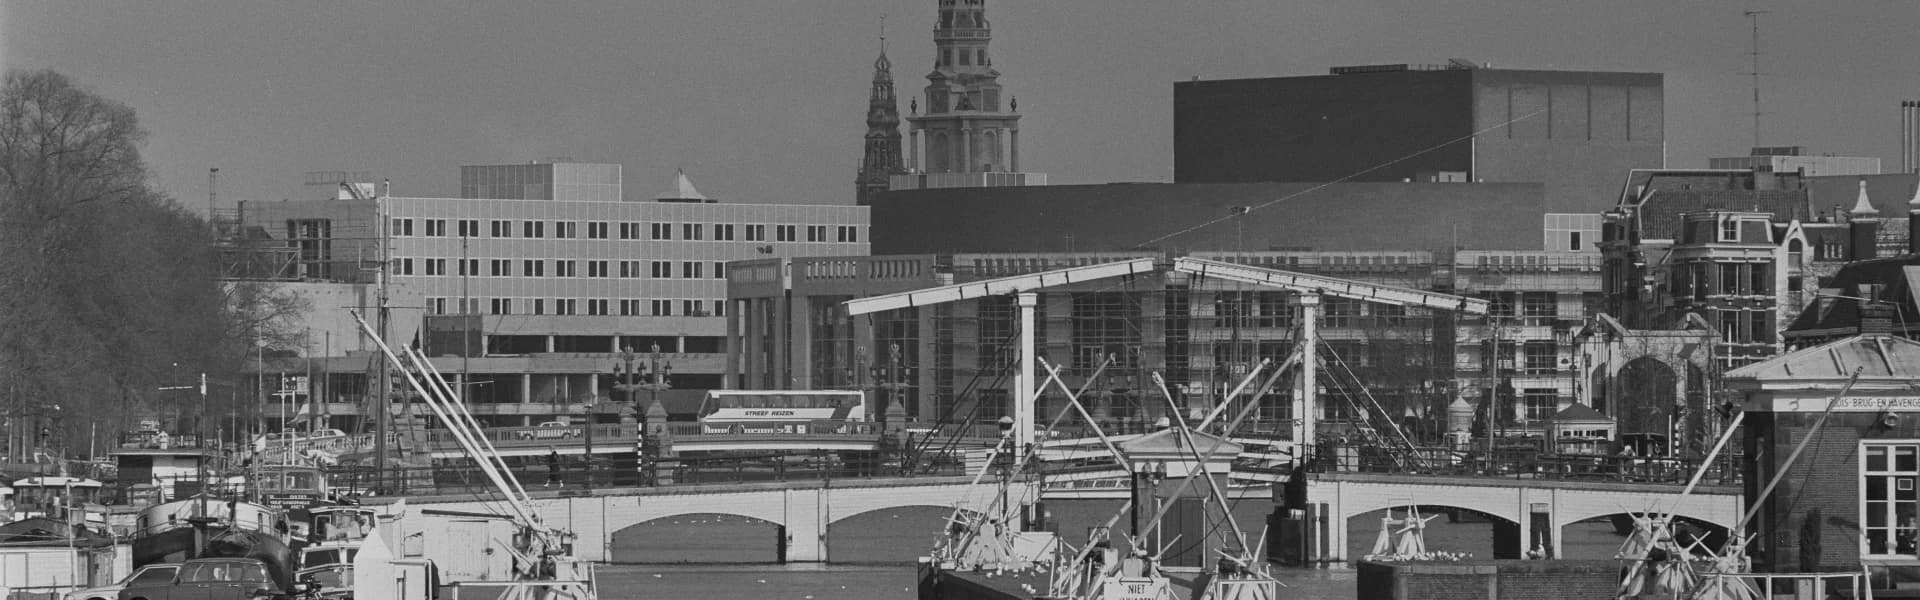
Utrecht
* 汇率仅供参考,基于ECB参考汇率
当地STR规定 — Utrecht
Short-stay letting is municipal. Amsterdam is tightly capped and requires notification/registration; other cities use local registration, housing-allocation and building rules.
市场分析 — Utrecht
关键需求驱动因素和主要投资风险
✅需求驱动因素
- •University demand
- •Rail connectivity
- •Professional services
- •Population growth
⚠️关键风险
- •High entry prices
- •Rent regulation
- •Limited stock
- •No primary STR yield
🇮🇱 以色列投资者须知
Israeli activity should be treated as limited for Utrecht. Use local counsel and property management; do not assume direct TLV flight coverage or Hebrew-service depth unless the buyer verifies current airline schedules and provider capacity.
学校:课程与教学语言
这里介绍本市儿童可选择的学校课程和教学语言,并不反映居住在此的外国居民人数。
公立学校:教学语言: Dutch · 来源
按名称字母顺序列出,并非排名或推荐。信息整理自公开来源;请向学校确认详情。
Utrecht待售房产
最新房源
显示 1–4 / 4 个房产

别墅 5卧 157m² 在Leidsche Rijn
别墅 2卧 74m² 在Wittevrouwen
别墅 5卧 129m² 在Overvecht
别墅 3卧 80m² 在Binnenstad
Yield by Neighborhood — Utrecht
微观区域投资对比——CASABROVA差异化
| 社区 | 价格/m² | STR收益率 | STR状态 | 特征 |
|---|---|---|---|---|
| Binnenstad | 暂无数据 | 3.38%–3.53% | 不可用 | |
| Lombok 入门价值中心 | 暂无数据 | 7%–9.3% | STR受限 🟡 | Lower-entry west-side flanking Utrecht Centraal; young/single household base, near-zero vacancy |
| Leidsche Rijn 家庭友好 | 暂无数据 | 5.7%–8.5% | STR受限 🟡 | Newer master-planned hub, A-label energy-efficient stock clears into free sector; corporate-expat families |
| Wittevrouwen | 暂无数据 | 6.4%–8.8% | STR受限 🟡 | |
| Overvecht | 暂无数据 | 8.65%–11.2% | 不可用 |
收益率和价格区间是基于公开房地产门户网站(Tranio、Investropa、Globes 等)的内部 AI 研究估算,并按季度刷新;并非一手来源数据。
Utrecht投资区域
Binnenstad
暂无数据
Lombok
Lower-entry west-side flanking Utrecht Centraal; young/single household base, near-zero vacancy
暂无数据
Leidsche Rijn
Newer master-planned hub, A-label energy-efficient stock clears into free sector; corporate-expat families
暂无数据
Wittevrouwen
暂无数据
Overvecht
暂无数据
编辑专栏 | CASABROVA
所有文章 →CASABROVA Global Investor Briefing — October 2026
The board barely moved: twenty-one of twenty-nine markets are unchanged, and the three that crossed two points did so because our own readings changed, not because anything happened in those markets. The top is now a three-way tie — Estonia 74.6, Poland 74.3, Slovenia 74.3 — with three tenths of a point between first and third.
CASABROVA Global Investor Briefing — September 2026
The Score did not move: no market changed by even half a point, and Estonia edged past Poland into #1 by 0.20 — inside the noise. What moved was the cost of money, and in opposite directions: New Zealand and Korea raised, Israel cut, Canada held, and 12-month Euribor crossed 3%. House prices rose in 25 of the 27 markets we can price for 2025, led by Hungary at +18.3%; only Canada and New Zealand fell.
2026 年第二季度投资者简报
我们的季度跨市场简报:二十九个市场、外国买家的借贷成本、周期位置、按国籍划分的税务以及 CASABROVA 评分。
全球投资者简报 — 2026年5月
本月评分保持稳定——真正的看点是谢克尔买家迎来的一代人一遇的汇率窗口、希腊成为资本撤出阶段的候选市场而西班牙出人意料地保持在峰值,以及三个市场从调整期进入复苏期。
市场评论 — Utrecht
The Netherlands is a deep, transparent market, but housing policy now sits at the centre of the investment case. Amsterdam offers liquidity, not easy yield; Rotterdam, The Hague, Utrecht and Eindhoven require regulation-by-asset checks.
The practical issue is not foreign ownership; it is whether the unit remains rentable at the assumed price under the regulated/mid-rent framework and municipal STR limits. Financing is available but must be stress-tested against low net yields.
CASABROVA treats the Netherlands as defensive only after rent-regime diligence. Avoid underwriting growth that depends on deregulation.
最后更新: 2026年5月11日